Buying a Condo in Pompano Beach
Half the city lives in larger buildings, and most of them are old enough for milestone inspections
The typical condo in Pompano Beach is worth about $245,906 on Zillow's home value index, down 4.5% over the past year, while single-family houses slipped only 0.8%. That gap is the story of the Pompano condo market right now: plenty of supply in older buildings, buyers asking hard questions about reserves, and sellers adjusting price to match.
- Typical condo value
- $246K Pompano Beach, Zillow, September 2026
- Past year
- −4.5%
- Past 5 years
- +12.6%
- Lower third of the market
- $203K typical value
- Upper third
- $652K typical value
A city where condos are the majority of homes
Census data shows 49.6% of Pompano Beach housing units are in buildings with ten or more units, against 29.0% single-family detached. The median year built for the city is 1974. Put those together and the typical Pompano condo is in a building that turned 30 well before the 2022 condo safety law took effect, which means it has been through, or is going through, a milestone inspection and a structural reserve study.
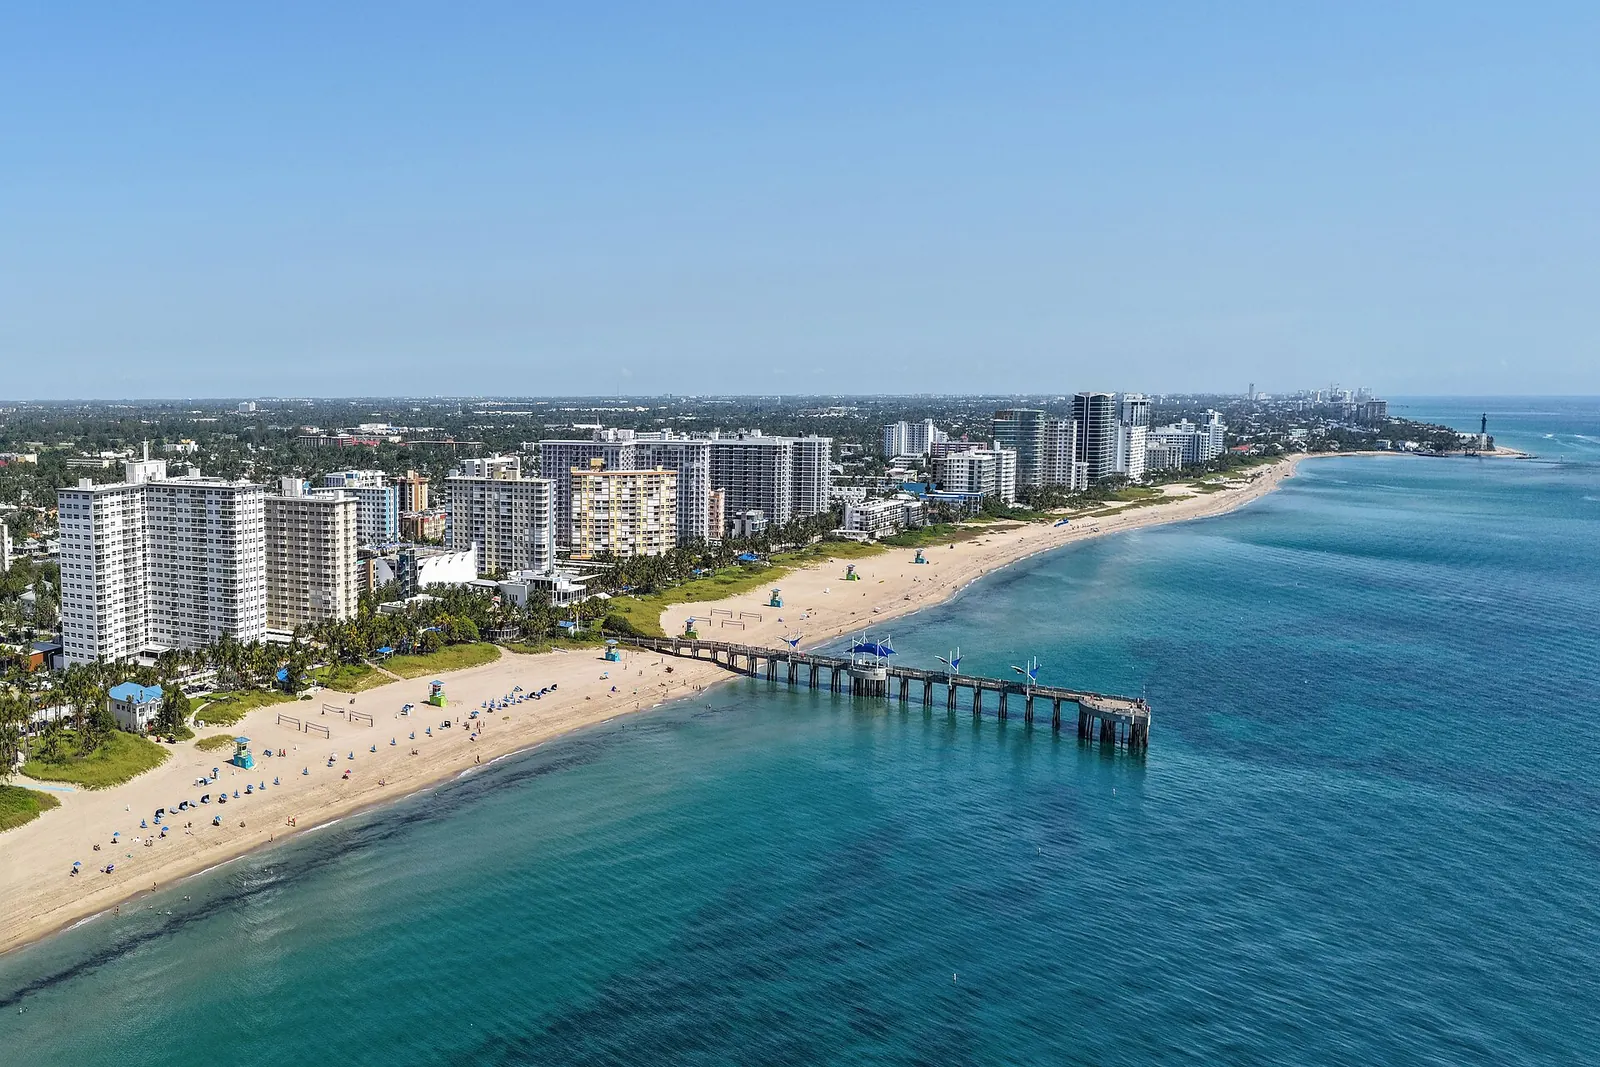
The stock splits roughly three ways. Beachfront and Intracoastal high-rises along A1A and the water, with the highest prices and the biggest structural budgets. Mid-rise and garden-style complexes between the Intracoastal and I-95. And large inland condo communities west of I-95, some built around golf courses, such as the Palm Aire area, where Zillow's neighborhood index is about $223,114.
Zillow Home Value Index, mid-tier, seasonally adjusted. Hover to see any date.
Data table
| Month | Condos | All homes |
|---|---|---|
| Dec 2012 | $112,933 | $125,944 |
| Dec 2013 | $129,513 | $147,599 |
| Dec 2014 | $143,400 | $164,873 |
| Dec 2015 | $152,243 | $178,290 |
| Dec 2016 | $158,812 | $192,592 |
| Dec 2017 | $168,419 | $213,190 |
| Dec 2018 | $180,382 | $229,934 |
| Dec 2019 | $185,262 | $240,441 |
| Dec 2020 | $195,465 | $256,346 |
| Dec 2021 | $228,777 | $300,681 |
| Dec 2022 | $289,698 | $362,402 |
| Dec 2023 | $303,574 | $381,776 |
| Dec 2024 | $282,234 | $373,577 |
| Dec 2025 | $252,528 | $351,249 |
| Sep 2026 | $245,906 | $350,137 |
Price levels by unit size
A one-bedroom in Pompano Beach runs about $166,589 and a two-bedroom about $295,957 on Zillow's bedroom indexes, which include houses as well as condos. Most one-bedrooms are condos, so the one-bedroom number is a fair guide to entry pricing. Two-bedroom condos vary widely, from inland garden units under that figure to direct-ocean units far above it.
Zillow's lower third of the market ends near $202,669. Much of what sits below that line is older one- and two-bedroom condos. The condo index at $245,906 is about 55% of the single-family figure of $445,858, a wider discount than in many Florida coastal cities, and much of the difference reflects building age and the cost of carrying an older building.
- 1 bedroom$167K
- 2 bedrooms$296K
- 3 bedrooms$439K
- 4 bedrooms$578K
- 5+ bedrooms$1.07M
Zillow index by bedroom count, all home types.
- Fort Lauderdale$403K
- Weston$306K
- Miramar$265K
- Hollywood$250K
- Pompano Beach$246K
- Davie$226K
- Plantation$204K
- Coral Springs$189K
- Pembroke Pines$187K
- Tamarac$152K
- Deerfield Beach$148K
- Sunrise$136K
- Lauderhill$112K
Zillow index.
Cash you need to buy at $246,000
| All cash | Mortgage, 20% down | Foreign national loan, 35% down | |
|---|---|---|---|
| Down payment | $246,000 | $49,200 | $86,100 |
| Buyer closing costs | $1,450 | $6,057 | $5,854 |
| Total at closing | $247,450 | $55,257 | $91,954 |
Includes Florida doc stamps on the note ($0.35 per $100 borrowed), the 0.2% intangible tax on the mortgage, the lender's title policy, settlement and recording fees and typical lender fees. Excludes prorated taxes and HOA. For your exact numbers use the closing cost calculator.
Reserves, SIRS and the milestone inspection
Under Florida's condo laws, buildings of three or more habitable stories need a milestone inspection by the end of the year they turn 30 (or 25 if the local building official requires it), then every 10 years. They also need a Structural Integrity Reserve Study every 10 years, and for budgets adopted on or after Dec 31, 2024, owners can no longer vote to waive or reduce those structural reserves. In buildings that underfunded reserves for years, that change shows up as higher monthly fees, a special assessment, or a loan the association repays through fees.
Before you sign, ask for these documents:
- The milestone inspection report, phase one and phase two if it went that far, and the status of any required repairs.
- The most recent SIRS and the current budget, so you can compare the funded reserve line with what the study calls for.
- Board minutes for the past 12 to 24 months, where talk of concrete repair, roof replacement or a bank loan appears first.
- Any adopted or proposed special assessment, with amount per unit and due dates.
- The master insurance policy and its renewal date.
On a resale, Florida gives you 7 days (weekends and legal holidays don't count) from receipt of the association package to cancel. Use those days to read it rather than skim it.
Building insurance and what it does to your fee
The association insures the structure, and that premium is part of your monthly fee. Older coastal buildings in Broward have seen large increases, and a building closer to the ocean usually carries a higher wind premium. Ask what the last renewal cost compared with the year before, and what the hurricane deductible is. A 5% deductible on a building insured for tens of millions is a large number, and the association has to have a plan for it.
You also need your own HO-6 policy for the interior, your belongings and loss assessment coverage. Get a quote during the inspection period. Flood coverage for the building is usually carried by the association if it is in a high-risk zone, but check, and consider your own contents flood policy on a ground-floor unit.
Financing a Pompano condo
Conventional lenders look at the building as well as the buyer. A building can be non-warrantable if it has pending structural repairs, an unfunded special assessment, significant litigation, too much commercial space, or a large share of units owned by one entity. Buyers in those buildings end up with portfolio loans, higher down payments, or cash. Ask your lender to run the condo questionnaire early, before inspections, so you don't pay for an inspection on a unit you can't finance.
With 20% down on a $245,906 condo, the loan is about $196,725, which means about $689 in note stamps and $393 in intangible tax. In Broward the seller usually pays deed stamps, and the buyer often pays for the owner's title policy by local custom. Pet limits, weight limits and lease-length rules are worth reading too, mostly because they affect who will buy the unit from you later.
Pompano condos against nearby options
On Zillow's all-homes figures, Pompano at $350,137 sits below Fort Lauderdale at $509,743 and above Deerfield Beach at $271,903 and Tamarac at $291,266. Buyers who want salt water within walking distance usually end up comparing Pompano with Deerfield and Fort Lauderdale. Those who care more about monthly cost than the beach drift west.
If you are leaning toward Pompano, the practical next step is a shortlist filtered by building age, milestone status and current fees, so you are only touring units you can finance and afford to carry.
Pompano Beach: questions and answers
How much is a condo in Pompano Beach?
Zillow's typical condo value in Pompano Beach is about $245,906, down 4.5% over the past year. One-bedroom homes in the city average about $166,589.
Are Pompano Beach condo prices dropping?
Condo values are down 4.5% over the past year on Zillow's index, a larger dip than single-family homes, which fell 0.8%.
What should I ask before buying a condo in an older Pompano building?
Ask for the milestone inspection, the structural reserve study, the budget, recent board minutes, any special assessments and the master insurance policy.
Can I get a mortgage on any Pompano Beach condo?
No. Buildings with pending structural work, litigation or underfunded reserves can be non-warrantable, which limits loan options. Have the lender review the building early.

Get a shortlist that fits your budget
Tell me what you're looking for and I'll send real listings with the full cost of owning each one: HOA or condo fees, property tax at your price, insurance, and closing costs. No newsletters, no pressure.
- MLS listings, including ones that just hit the market
- Condo budget, reserves and inspection history checked before you offer
- Fully remote if you need it: video tours, e-signing, wire to escrow
Or reach me directly: (754) 203-9632 · [email protected] · WhatsApp on the same number
Run the numbers for your purchase
Data: Zillow Home Value Index (ZHVI), Zillow Research, latest month September 2026; U.S. Census Bureau, American Community Survey 2020–2024 5-year estimates. Figures for small areas carry margins of error. These are planning numbers, not an appraisal of any property.