Buying a House in Tampa
City limits or the suburbs: what $395,000 buys, and the costs that change the math.
The typical single-family house in Tampa is worth about $395,087 on Zillow's home value index, essentially flat over the past year at 0.4%, after all home values in the city rose 20.4% over five years. Prices have stopped climbing, so the real decision for most buyers now is whether to buy inside the city or in a Hillsborough suburb, and how flood, insurance and taxes change the monthly payment in each.
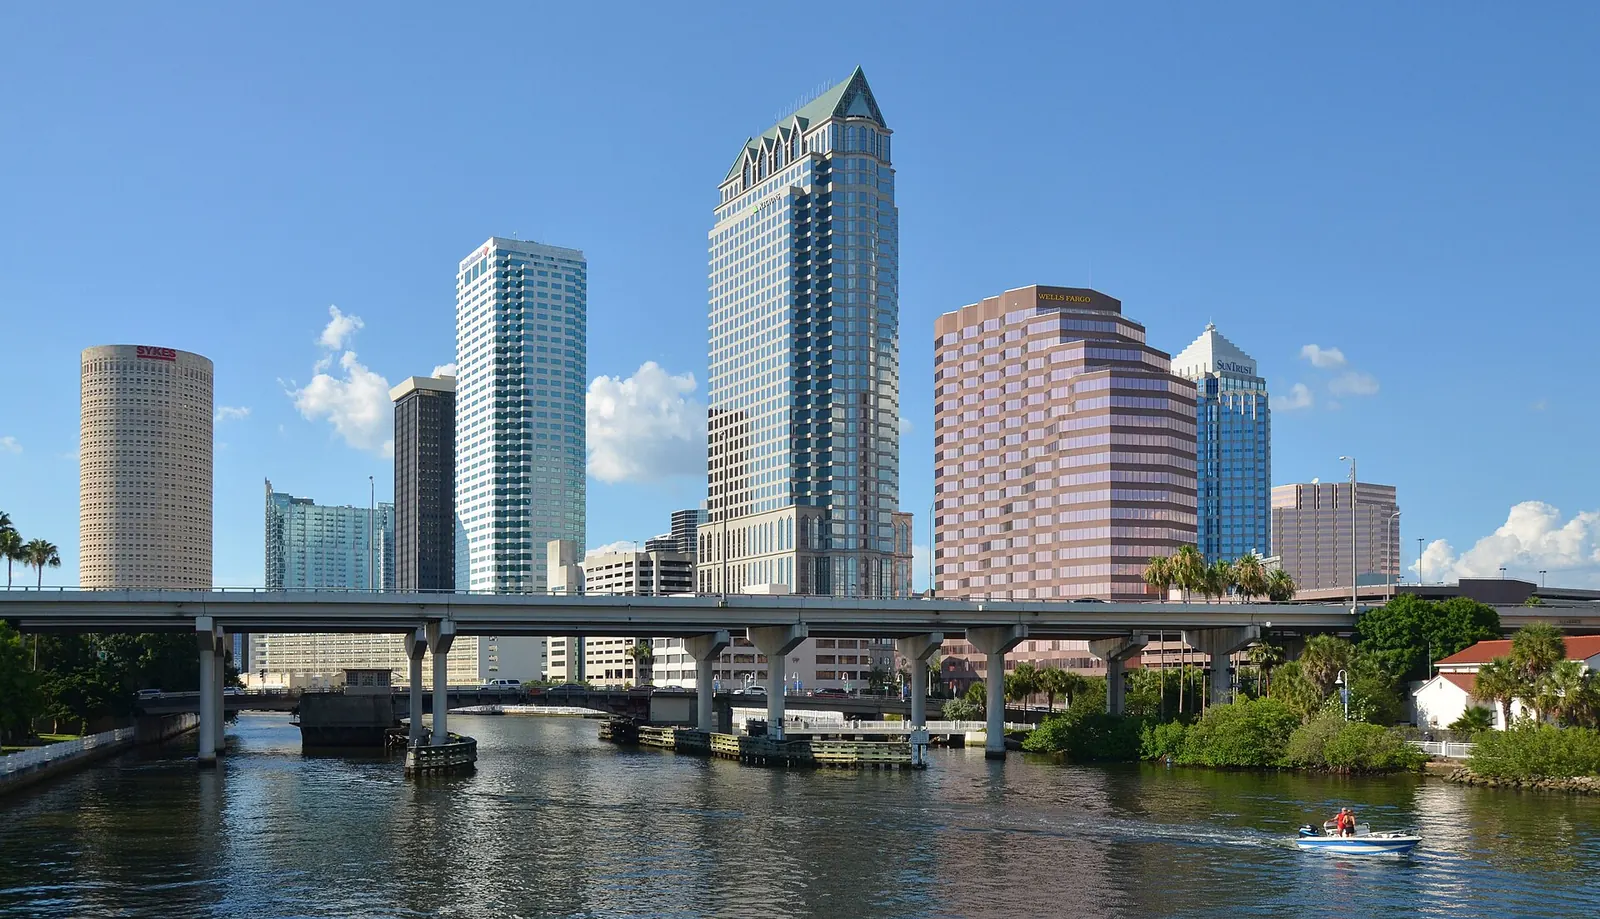
- Typical single-family home value
- $395K Tampa, Zillow, September 2026
- Past year
- +0.4%
- Past 5 years
- +20.8%
- Lower third of the market
- $240K typical value
- Upper third
- $689K typical value
Bedrooms and price bands inside the city
Zillow's bedroom numbers for Tampa: a two-bedroom is about $266,265, a three-bedroom about $382,026, a four-bedroom about $561,556, and five or more about $901,564. Going from three to four bedrooms adds about $179,500. The lower third of the market tops out near $239,812 and the upper third starts near $688,736.
Inside the city, the price of a three-bedroom depends heavily on location. Older bungalows and block homes in neighborhoods north of downtown sit at the low end of the range, while South Tampa homes near Bayshore Boulevard sit far above it. The neighborhood page breaks those numbers down. On this page I focus on what changes the cost of owning any of them.
One pattern I see often: buyers set a budget around the typical value, then find that the houses in that band inside the city are older and smaller than what the same money buys a short drive out. Decide early which matters more to you, the location or the house itself, because that single choice narrows the search faster than any filter.
Zillow Home Value Index, mid-tier, seasonally adjusted. Hover to see any date.
Data table
| Month | Single-family | All homes |
|---|---|---|
| Dec 2012 | $113,599 | $109,930 |
| Dec 2013 | $135,883 | $131,281 |
| Dec 2014 | $150,795 | $145,119 |
| Dec 2015 | $171,094 | $163,822 |
| Dec 2016 | $196,773 | $187,616 |
| Dec 2017 | $218,039 | $208,004 |
| Dec 2018 | $235,129 | $224,793 |
| Dec 2019 | $248,036 | $237,482 |
| Dec 2020 | $278,129 | $265,578 |
| Dec 2021 | $338,796 | $323,523 |
| Dec 2022 | $399,271 | $382,955 |
| Dec 2023 | $410,686 | $392,306 |
| Dec 2024 | $410,834 | $391,097 |
| Dec 2025 | $393,334 | $373,729 |
| Sep 2026 | $395,087 | $375,619 |
Suburbs that cost less, and the ones that cost more
Tampa's all-homes typical value is about $375,619. Nearby Hillsborough communities, on Zillow's index:
- Below Tampa: Sun City Center $269,061 (largely a retirement community), Ruskin $309,768, Temple Terrace $323,921, Plant City $337,742, Wimauma $344,049, Seffner $351,494, Brandon $353,216, Riverview $363,056.
- Above Tampa: Valrico $413,453, Citrus Park $421,744, Lutz $486,345, Odessa $684,962.
Riverview and Brandon are where many buyers end up when they want a newer house with a yard for roughly the city's average price. The trade is the commute and, in many newer subdivisions, HOA fees and a Community Development District (CDD) assessment on the tax bill. Lutz and Odessa to the north cost more, often because of larger lots and lakefront homes. For a fair comparison, add the CDD and HOA to the mortgage and tax before you call a suburb cheaper.
- 1 bedroom$158K
- 2 bedrooms$266K
- 3 bedrooms$382K
- 4 bedrooms$562K
- 5+ bedrooms$902K
Zillow index by bedroom count, all home types.
- Odessa$687K
- Lutz$504K
- Citrus Park$423K
- Valrico$415K
- Tampa$395K
- Temple Terrace$373K
- Riverview$366K
- Brandon$357K
- Seffner$352K
- Wimauma$344K
- Plant City$339K
- Ruskin$311K
- Sun City Center$306K
Zillow index.
Cash you need to buy at $395,000
| All cash | Mortgage, 20% down | Foreign national loan, 35% down | |
|---|---|---|---|
| Down payment | $395,000 | $79,000 | $138,250 |
| Buyer closing costs | $1,450 | $6,713 | $6,387 |
| Total at closing | $396,450 | $85,713 | $144,637 |
Includes Florida doc stamps on the note ($0.35 per $100 borrowed), the 0.2% intangible tax on the mortgage, the lender's title policy, settlement and recording fees and typical lender fees. Excludes prorated taxes and HOA. For your exact numbers use the closing cost calculator.
Flood risk after the 2024 storms
The 2024 hurricane season flooded parts of the Tampa area that many owners had considered safe, especially low-lying neighborhoods near the bay. Buyers now ask about flooding first, and they should. What I recommend for every house:
- Look up the FEMA flood zone for the exact address. In an A or V zone, a lender will require flood insurance, which is separate from the homeowners policy.
- Ask the seller in writing whether the house has ever flooded or had a flood claim, and read the disclosure.
- Ask for an elevation certificate if one exists; it can lower the flood quote.
- Get a flood quote even outside a high-risk zone. In lower-risk zones it is often inexpensive.
Inland suburbs are not automatically safe from flooding either. Rivers, retention ponds and drainage can matter as much as distance from the bay.
Insurance on a 1980s Tampa house
Census data puts the median year built for Tampa housing at 1985, and about half of all units (50.3%) are single-family detached homes. Many houses on the market are 35 to 60 years old. For those, insurers usually want a 4-point inspection covering roof, electrical, plumbing and HVAC, and they price the wind portion of the policy off a wind mitigation inspection.
Roof age carries the most weight. An older shingle roof can mean a higher premium or no offer from some carriers, and Citizens Property Insurance, the state-backed insurer of last resort, may become the fallback. A recent roof with a permit, hurricane straps or clips, and impact windows or shutters all help. Put the quote inside your inspection period so it can still change your offer.
Your tax bill will not match the seller's
Florida resets the assessed value to market value after a sale. A long-time owner in a Tampa house that has doubled in value may pay tax on a fraction of what you pay.
If the house becomes your permanent Florida residence, homestead takes up to $51,411 off the assessed value in 2026, and Save Our Homes keeps future assessment increases to 3% or CPI. File with the Hillsborough County Property Appraiser after you close. A second home gets no homestead exemption and a 10% cap on non-school levies. Amendment 3 on the November 3, 2026 ballot could change parts of this; it needs 60% and the result was unknown at writing. Florida also has no state income tax, which matters to buyers moving from high-tax states.
What a buyer pays to close on a typical Tampa house
On a $395,087 house with 20% down, the down payment is about $79,000 and the loan about $316,100. The buyer typically pays note stamps of $0.35 per $100 of the loan (about $1,106) and intangible tax of 0.2% (about $632), plus lender charges, title, prepaid insurance and escrow. In Hillsborough the seller usually pays the deed stamps of $0.70 per $100. The cash-to-close table on this page lays it out. This isn't legal or tax advice; your lender's Loan Estimate is the number to trust. If you're weighing the city against Brandon or Riverview, a shortlist of houses in both lets you compare total monthly cost directly.
What buyers ask me
Is it a good time to buy a house in Tampa?
I don't predict prices. Zillow shows Tampa house values up 0.4% over the past year after a 20.4% five-year rise for all homes, so the market has flattened. Your timing should depend on rates, the insurance quote on the specific house, and how long you'll stay.
How much do I need to buy a house in Tampa?
On a typical $395,087 house with 20% down, that's about $79,000 plus closing costs. State taxes on the mortgage alone are about $1,700. Lower-down-payment loans need less upfront but add mortgage insurance.
Is it cheaper to buy in Brandon or Riverview than Tampa?
Slightly, on Zillow's data: Brandon is about $353,216 and Riverview about $363,056 versus $375,619 for all Tampa homes. Check HOA and CDD fees, which are common in newer suburban subdivisions.
Do I need flood insurance for a house in Tampa?
Your lender requires it in FEMA A or V zones. Outside those, it's optional, but after the 2024 storms I recommend getting a quote on every house during the inspection period.

Get a shortlist that fits your budget
Tell me what you're looking for and I'll send real listings with the full cost of owning each one: HOA or condo fees, property tax at your price, insurance, and closing costs. No newsletters, no pressure.
- MLS listings, including ones that just hit the market
- Condo budget, reserves and inspection history checked before you offer
- Fully remote if you need it: video tours, e-signing, wire to escrow
Or reach me directly: (754) 203-9632 · [email protected] · WhatsApp on the same number
Run the numbers for your purchase
Data: Zillow Home Value Index (ZHVI), Zillow Research, latest month September 2026; U.S. Census Bureau, American Community Survey 2020–2024 5-year estimates. Figures for small areas carry margins of error. These are planning numbers, not an appraisal of any property.