Buying a House in Hialeah
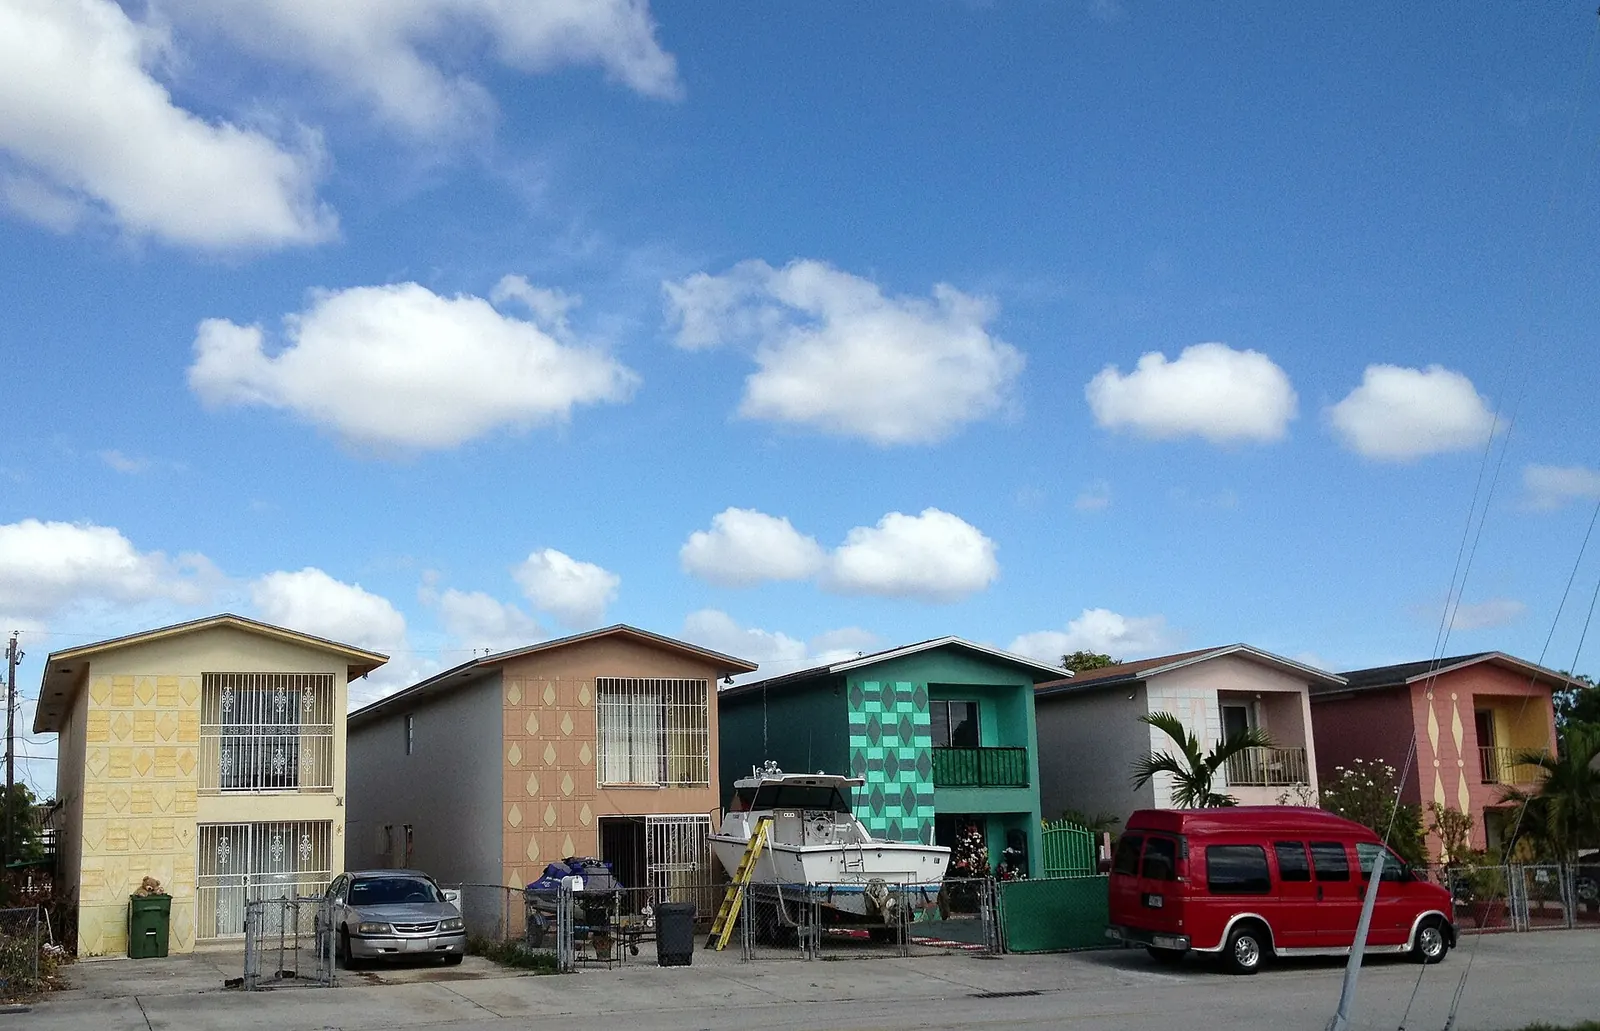
Mostly one-story block houses from the 1950s to the 1980s, priced below Doral and Miami.
A typical single-family house in Hialeah is worth about $565,104 on Zillow's home value index, up 1.2% over the past year while the city's condos fell. Most of these houses are decades old, with a citywide median year built of 1975 in Census data, so the cost of buying one here includes what the inspection turns up.
- Typical single-family home value
- $565K Hialeah, Zillow, September 2026
- Past year
- +1.2%
- Past 5 years
- +36.3%
- Lower third of the market
- $248K typical value
- Upper third
- $628K typical value
Prices by size and where Hialeah sits locally
Zillow's bedroom figures for Hialeah:
- Three bedrooms: about $531,319
- Four bedrooms: about $655,015
- Five bedrooms or more: about $742,681
The step from three to four bedrooms is about $124,000, and the step from four to five is smaller, about $88,000. The upper third of the market starts near $628,419. Over five years, Hialeah's all-homes value rose 35.7%.
Nearby, Doral's typical house is $681,680, about $116,000 more. All-homes figures for North Miami ($421,601) and Miami Gardens ($474,495) sit below Hialeah's $443,765, while Miami is at $583,705. Hialeah's draw is a central location, by the airport and along the Palmetto Expressway, at a price below its western and southern neighbors.
Zillow Home Value Index, mid-tier, seasonally adjusted. Hover to see any date.
Data table
| Month | Single-family | All homes |
|---|---|---|
| Dec 2012 | $167,849 | $121,176 |
| Dec 2013 | $197,455 | $144,305 |
| Dec 2014 | $224,427 | $166,603 |
| Dec 2015 | $251,962 | $189,960 |
| Dec 2016 | $282,945 | $216,951 |
| Dec 2017 | $311,461 | $241,665 |
| Dec 2018 | $333,875 | $261,217 |
| Dec 2019 | $347,860 | $274,713 |
| Dec 2020 | $375,806 | $297,281 |
| Dec 2021 | $423,193 | $334,049 |
| Dec 2022 | $498,148 | $397,528 |
| Dec 2023 | $543,112 | $436,628 |
| Dec 2024 | $575,568 | $458,382 |
| Dec 2025 | $559,591 | $442,860 |
| Sep 2026 | $565,104 | $443,765 |
Inspecting a 1950s to 1980s block house
Most Hialeah houses are one-story concrete block on slab. The block holds up well. The systems inside often don't. On a house of this age, I ask the inspector to focus on:
- Drain lines. Many older South Florida homes have cast iron drain pipes under the slab, which corrode over time. A camera scope of the main line costs little next to a repair.
- Supply plumbing. Look for galvanized steel or polybutylene, both of which insurers dislike.
- Electrical. Check the panel's brand and age, the capacity, and any aluminum branch wiring.
- Roof. Get the permit date for the last replacement and the type of underlayment.
- Additions. Rooms added at the back, enclosed porches and converted garages are common here. Check each against the county permit record.
Insurers usually want a 4-point inspection on older homes, covering roof, electrical, plumbing and HVAC, and a wind mitigation report can bring the premium down. Order both during your inspection period.
- 1 bedroom$185K
- 2 bedrooms$266K
- 3 bedrooms$531K
- 4 bedrooms$655K
- 5+ bedrooms$743K
Zillow index by bedroom count, all home types.
- Miami Beach$2.46M
- Coral Gables$2.1M
- Doral$682K
- Miami$664K
- Aventura$636K
- The Hammocks$597K
- Cutler Bay$592K
- Hialeah$565K
- North Miami Beach$508K
- North Miami$505K
- Miami Gardens$484K
- Fountainbleau$474K
- Homestead$455K
Zillow index.
Cash you need to buy at $565,000
| All cash | Mortgage, 20% down | Foreign national loan, 35% down | |
|---|---|---|---|
| Down payment | $565,000 | $113,000 | $197,750 |
| Buyer closing costs | $4,350 | $10,361 | $9,895 |
| Total at closing | $569,350 | $123,361 | $207,645 |
Includes Florida doc stamps on the note ($0.35 per $100 borrowed), the 0.2% intangible tax on the mortgage, the lender's title policy, settlement and recording fees and typical lender fees, plus the owner's title policy, which Miami-Dade buyers usually pay. Excludes prorated taxes and HOA. For your exact numbers use the closing cost calculator.
Unpermitted work and why it matters at closing
Open or missing permits are among the most common problems I see with older Miami-Dade houses. A lender's appraiser may not count unpermitted square footage, which can lower the appraised value. An insurer may refuse to cover an addition it can't verify. And the next buyer's agent will look for the same thing when you sell.
Run a permit search with the city and county early. If work was done without permits, you can ask the seller to legalize it before closing, negotiate a price that reflects the cost of doing it yourself, or walk away within your inspection period.
Garage conversions deserve a specific look. A converted garage with its own exterior door, a kitchenette or a separate meter may have been used as a separate unit, and the city treats that differently from a family room. Ask the seller what was done and when, and check whether the property's zoning and permits match how the space is used today.
Flood zones and insurance quotes
Hialeah is flat, low and crossed by canals. Look up the FEMA flood map for the address. In a high-risk A zone, a lender will require flood insurance, sold separately from homeowners coverage through the NFIP or a private carrier, and the elevation certificate will drive the price. Outside an A zone, flood coverage is optional but worth pricing.
Get a homeowners quote during your inspection period, before you are committed. Roof age and opening protection drive the number. The hurricane deductible on a Florida policy is a percentage of the dwelling amount, 2%, 5% or 10%, and applies once per calendar year. On a house insured at $565,104, a 2% deductible is about $11,300. If private carriers won't write the house, Citizens Property Insurance is the last-resort option.
Closing costs and the tax reset
Miami-Dade's deed stamps on a single-family house are $0.60 per $100, about $3,391 at $565,104, and the seller usually pays them. In this county, the buyer usually pays for the owner's title insurance, which is priced at a state-set rate. With 20% down, the note stamps and intangible tax on a $452,083 loan come to about $2,486, before lender fees and prepaid items.
The bigger surprise for many buyers is the property tax bill. Hialeah has many long-time owners, and their assessments have grown slowly under Save Our Homes. Your purchase resets the Hialeah assessment to current market value. File for homestead if it's your permanent residence: up to $51,411 off assessed value in 2026, and a 3% or inflation cap on future increases. Florida has no state income tax. This isn't legal or tax advice.
Is a Hialeah house a good buy
For a buyer who wants a detached house in central Miami-Dade under $600,000, Hialeah is one of the few places with real inventory at that level. House values rose last year while condos fell, so sellers of houses have not had to cut much. The trade-off is age: you are buying a structure that is often 40 to 70 years old and has been updated unevenly.
The best purchases here are houses where the roof, plumbing and electrical have been redone with permits, since those cost less to insure and have fewer surprises. If you share your budget and the bedroom count you need, I'll put together a shortlist and flag the permit history on each.
What buyers ask me
How much is a house in Hialeah?
Zillow's typical single-family value in Hialeah is about $565,104. Three-bedrooms run near $531,319 and four-bedrooms near $655,015.
Is Hialeah a good place to buy a house?
It has detached homes in central Miami-Dade below Doral and Miami prices. Most houses are older, so budget for inspections and updates.
What inspections do I need for an older Hialeah house?
A full home inspection, a 4-point inspection for insurance, a wind mitigation report and ideally a camera scope of the drain line. Add a permit search on any additions.
What does it cost to close on a house in Hialeah?
With a loan, expect note stamps, intangible tax, title insurance, lender fees and prepaid taxes and insurance. On a $452,083 loan, the stamps and intangible tax alone are about $2,486.

Get a shortlist that fits your budget
Tell me what you're looking for and I'll send real listings with the full cost of owning each one: HOA or condo fees, property tax at your price, insurance, and closing costs. No newsletters, no pressure.
- MLS listings, including ones that just hit the market
- Condo budget, reserves and inspection history checked before you offer
- Fully remote if you need it: video tours, e-signing, wire to escrow
Or reach me directly: (754) 203-9632 · [email protected] · WhatsApp on the same number
Work out your own numbers
Data: Zillow Home Value Index (ZHVI), Zillow Research, latest month September 2026; U.S. Census Bureau, American Community Survey 2020–2024 5-year estimates. Figures for small areas carry margins of error. These are planning numbers, not an appraisal of any property.